Venture capital headlines in Southeast Asia are sending mixed signals in 2026. One view shows stabilization through a sharp jump in deployed capital. Tracxn counted $12.8bn raised across 178 equity rounds from January to July 2026, versus $5.42bn across 255 rounds in the same window of 2025. That implies capital up 137% year on year, while the number of funded rounds fell 30%, and average round size rose from $21m to $72m. Read together, this is not a broad-based surge. It is a higher bar market where fewer companies get funded, but the ones that do can raise much larger checks.
Quarterly detail reinforces the same pattern of concentration. DealStreetAsia’s Q1 2026 snapshot showed $2.81bn across 98 equity deals, the lowest quarterly deal count in at least eight years, with a single round carrying more than 70% of the quarter’s capital. Country splits also highlight how activity clusters. In Q1 2026, Singapore accounted for 91.5% of total capital raised in Southeast Asia, and its share of regional deal volume has stayed above 50% since Q2 2022. Malaysia was a notable outlier for activity, ranking second in Q1 2026 with 18 deals, its highest quarterly tally since Q3 2024, driven mainly by Seed and earlier-stage rounds.
Why “More Capital” Can Still Mean a Tougher Market
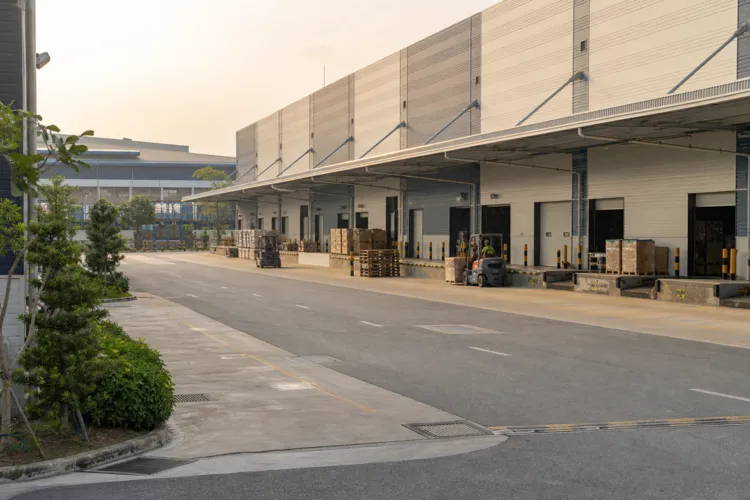
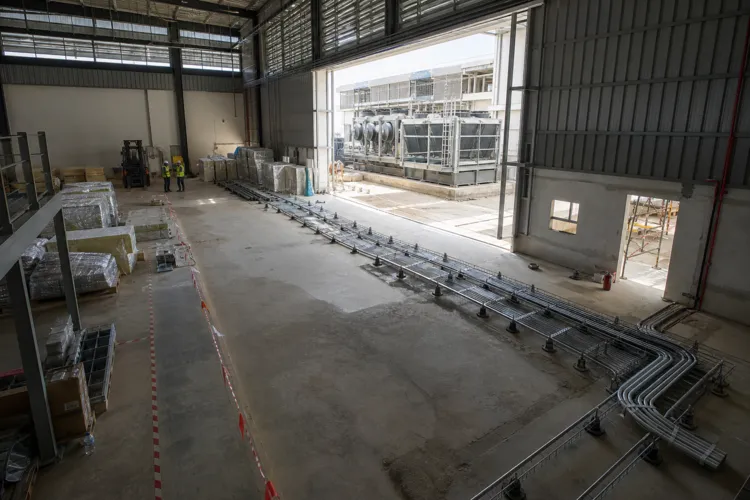
Much of the 2026 uplift is tied to mega-round distortions that do not always reflect operating startup demand in ASEAN markets. Second Talent noted that three of the five largest rounds of the past two years are data centre or AI infrastructure, and that two of those are not Southeast Asian operating businesses at all. Examples include DayOne Data Centers, which announced over $2bn in Series C financing in January 2026. It is Singapore-headquartered, a spin-out of Shanghai-listed GDS Holdings, and is building capacity in Finland, Johor, Batam, Thailand, and Japan. Another distortion came from Kling AI: Kuaishou raised $2.8bn for its AI video unit in July 2026 at a $15bn pre-money valuation, backed by Alibaba, Tencent, and Baidu, and described as a Chinese product with a Chinese market that still shows up in regional tallies via an offshore round.
Underneath the headline numbers, investor behavior points to disciplined deployment and a push for profitability. DealStreetAsia described Southeast Asia in early 2026 as “stabilising at a lower base rather than staging a meaningful rebound,” with investors prioritising clearer paths to profitability, stronger governance, and more disciplined capital deployment. This lines up with Second Talent’s broader Asia framing after a “pivotal reset in 2025,” where the ecosystem entered 2026 with a sharper focus on profitability and sustainable growth. Even in that broader Asia context, funding in H1 2025 declined to $26.2 billion, down approximately one-third year over year, while fintech and AI/ML represented 41% of total deal value and late-stage funding remained constrained.
Fundraising conditions add another constraint to the ASEAN startup funding rebound 2026 story. DealStreetAsia DATA VANTAGE reported that no dedicated Southeast Asia private equity fund reached a final close in H1 2026, and that the only venture capital vehicle to complete its raise was TheVentures’ $8 million fund, managed by a South Korean GP. The same review noted that no Southeast Asia-headquartered VC manager had reported a final close by August. In parallel, TechTimes reported that three pan-Asian mega-funds held a combined $39.2 billion in commitments in H1 2026, accounting for roughly 85% of all Asia Pacific private equity capital raised in the first half. For founders, the practical implication is simple: plan around revenue delivery on the round already closed, because capital can be abundant at the top yet scarce for most companies trying to raise.
What do the 2026 Southeast Asia funding numbers say about market conditions?
Why can funding look higher even when startups say fundraising is hard?
Which market dominated Southeast Asia startup funding in Q1 2026?
How does the ASEAN startup funding rebound narrative in 2026 connect to profitability?